×

The Standard e-Paper
Home To Bold Columnists
 The Standard Group Plc is a
multi-media organization with investments in media platforms spanning newspaper
print operations, television, radio broadcasting, digital and online services. The
Standard Group is recognized as a leading multi-media house in Kenya with a key
influence in matters of national and international interest.

Audio By Vocalize
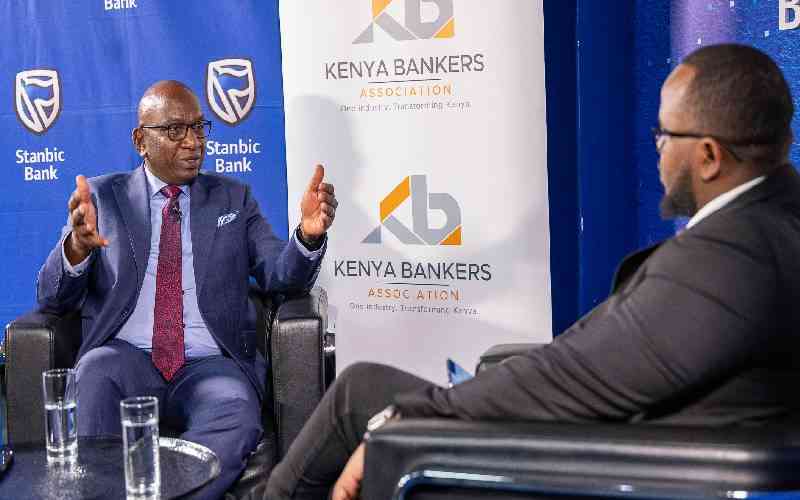
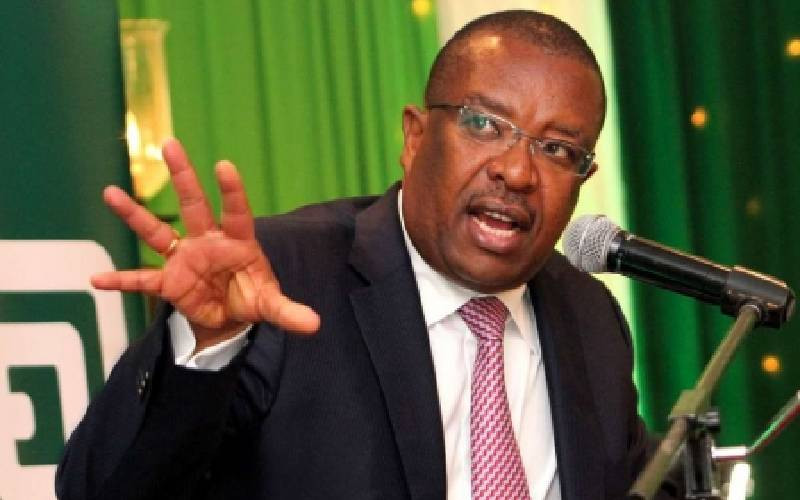
Entrepreneurs who mistake optimism for a business strategy risk committing capital to ventures that may not survive the realities of the market, Prime Bank Managing Director Rajeev Pant has warned.
Speaking during ongoing interviews with bankers dubbed MyChat with a Bank CEO, Pant urged business owners to base investment decisions on evidence, develop realistic financial plans and remain flexible enough to adjust their strategies when circumstances change.
“That's a hope or a prayer. That's not a plan. You need to have a plan and you need to stick to that plan. You can flex the plan; that's not a problem. But it has to be based on some basic facts,” he said.
His message comes at a time when businesses are navigating high operating costs, uncertain demand and constrained access to formal credit. For entrepreneurs, the challenge is not simply identifying an attractive opportunity, but determining whether the business can generate sufficient cash flow to sustain operations, meet its financial obligations and deliver returns.
Pant's advice highlights the importance of financial discipline before committing money to a new venture or expanding into unfamiliar markets. Business owners need to understand the capital required, the likely costs of running the enterprise, the expected revenue and the risks that could undermine their projections.
This is particularly important for small and medium-sized enterprises (SMEs), which often have limited financial reserves to absorb unexpected expenses or prolonged periods of weak sales. A business plan built on overly optimistic sales forecasts or underestimated operating costs can quickly translate into cash-flow difficulties.
The financing environment makes such discipline even more critical. According to the Central Bank of Kenya's (CBK) 2024 Survey Report on Micro, Small and Medium Enterprises (MSMEs) Access to Bank Credit, the number of active loans held by MSMEs fell by 24.7 per cent to 890,000 in December 2024 from 1.18 million in December 2022.
The decline points to the difficulties smaller enterprises face in accessing formal bank financing, making it important for entrepreneurs to assess their funding needs and repayment capacity before taking on debt.
Despite the decline in loan accounts, the value of outstanding MSME loans remained almost unchanged at Sh784.4 billion, compared with Sh783.3 billion two years earlier.
The regulator attributed the decline in active accounts partly to high lending rates and subdued consumer demand, pointing to the financial pressures facing businesses seeking to borrow.
The average interest rate on MSME loans stood at 16.4 per cent for commercial banks and 26.3 per cent for microfinance banks in December 2024.
These financing conditions make financial planning an important consideration for entrepreneurs, particularly those who depend on borrowed money to establish or expand their operations.
A separate study by the Kenya Bankers Association (KBA) found that 70 per cent of MSMEs reported difficulties accessing credit from formal financial institutions.
The April 2025 policy brief, based on a survey of 886 enterprises across all 47 counties, identified inadequate documentation, lack of collateral and high interest rates among the barriers affecting access to bank financing.
The findings also showed that the size of an enterprise and its turnover influenced its ability to secure credit, suggesting that businesses at different stages of growth face different financing challenges.
Stay informed. Subscribe to our newsletter
For entrepreneurs, developing a business idea is only one part of preparing to operate an enterprise. They also need financial records and documentation that demonstrate how the business operates and its capacity to meet financial obligations.
Pant emphasised that having a plan based on facts speaks to the need for business owners to understand their financial position before making investment commitments. Beyond accessing loans for expansion, businesses also need money to sustain their daily operations.
Financial Sector Deepening Kenya (FSD Kenya), published a report in May 2024 that found out that micro and small enterprises mainly sought financing for working capital rather than long-term investment.
The research identified savings, social networks and credit from suppliers as important sources of liquidity for businesses.
It also found that rising supply costs, weaker demand and compliance expenses were putting pressure on small enterprises, affecting their revenues, profits and ability to remain resilient.
These challenges mean that entrepreneurs must consider more than the initial cost of setting up a business. They need to account for recurring expenses, the time taken to receive payments from customers and the resources required to maintain operations.
A business may have a promising product or service but still struggle if it cannot meet its daily operating costs or maintain sufficient cash flow.
The Prime Bank chief also discussed the decision facing entrepreneurs considering opportunities outside Kenya, including whether to invest in foreign markets or concentrate on industries they understand locally.
He also examined the growing role of artificial intelligence (AI) in financial services, particularly its use in customer service and the changing relationship between banks and their customers.
Pant discussed how automated systems can handle customer interactions and connect users to services, while noting that human engagement remains part of the banking relationship.
The CBK's 2025 Survey on Artificial Intelligence in the Banking Sector found that 50 per cent of surveyed financial institutions had adopted AI, with applications including credit scoring, fraud detection and customer engagement.
The survey covered 37 commercial banks, one mortgage finance institution, 14 microfinance banks, three credit reference bureaus and 70 digital credit providers.
The findings point to the growing adoption of AI in Kenya's financial services industry as institutions explore ways to improve efficiency, customer engagement and risk management.
Reflecting on Prime Bank's experience working with entrepreneurs, the banker observed that the institution had grown over the past 35 years and had witnessed businesses develop their ideas into enterprises.
Subscribe to our newsletter and stay updated on the latest developments and special offers!